Coverage: Original stickers: Ford and Lincoln from Ford, most 2017-on Jeep, Ram, Dodge and Chrysler from Stellantis, recent Subaru. Other brands when on file
How does an insurer value a totaled car?
When repairs would cost more than the car is worth, the insurer pays its actual cash value: what the car was worth just before the loss. To get there, most insurers use a valuation report built from comparable vehicles for sale near you. They adjust each comparable for differences in mileage, condition and options.
State rules spell out parts of this. New Jersey’s total-loss rule says the valuation source must produce values of substantially similar vehicles and “shall include all major options” (N.J.A.C. 11:3-10.4). Oregon’s insurance regulator tells drivers to “make sure the vehicles are comparable (make, model, mileage, options)” (Oregon DFR).
So options aren’t a detail. If your car had a $5,000 package and the report treats it as a base model, the comparables are wrong and the offer comes in low.
Why do packages go missing from valuation reports?
The report usually starts from the VIN, and the VIN carries less than people think. It identifies the model, body, drive, engine and often a trim group. It doesn’t list most factory packages, paint upgrades or dealer-installed accessories. Anything the VIN can’t show has to be added by someone, and that step is where options get lost.
A real example: what the VIN misses on a Ram 2500
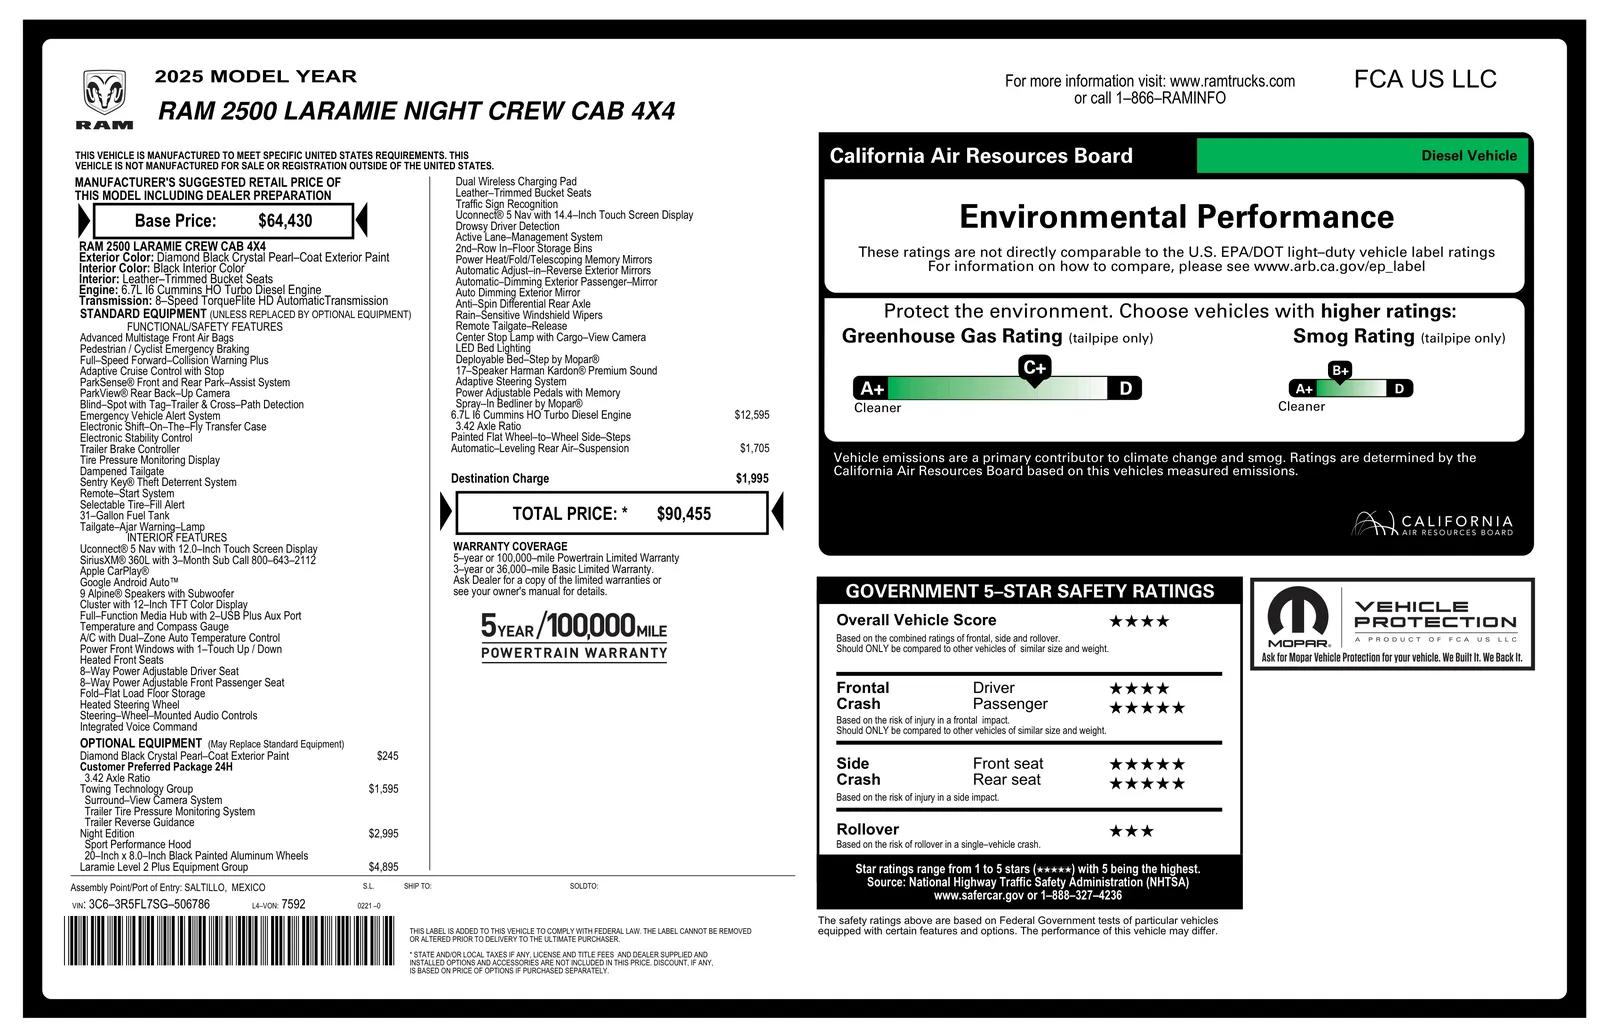
Take a 2025 Ram 2500 Laramie Crew Cab 4x4, VIN 3C63R5FL7SG506786. NHTSA’s free decoder calls it a Laramie, and that’s all it says about trim. Here is what the original window sticker from Stellantis lists:
| Line on the sticker | Price | In a plain VIN decode? |
|---|---|---|
| Base price, Ram 2500 Laramie Crew Cab 4x4 | $64,430 | Yes, as “Laramie” |
| 6.7L I6 Cummins HO turbo diesel | $12,595 | Engine family, yes |
| Laramie Level 2 Plus Equipment Group | $4,895 | No |
| Night Edition | $2,995 | No |
| Painted side steps, automatic-leveling rear air suspension | $1,705 | No |
| Towing Technology Group | $1,595 | No |
| Diamond Black Crystal Pearl-Coat paint | $245 | No |
| Destination charge | $1,995 | No |
| Total price | $90,455 |
That’s $11,435 of options the decoder never mentions. A used truck’s value doesn’t move dollar for dollar with original option prices. Still, a report that prices this truck as a plain Laramie diesel is comparing it with the wrong trucks.
How to use the sticker in your claim
- Get the valuation report. Ask the insurer for the full report, with its list of comparables. Washington’s regulator says the insurer “might not provide this report unless you ask for it” (Washington OIC).
- Check the options line by line. Compare the equipment listed for your car with the sticker. Note every package, engine, paint or accessory the report left out.
- Check the comparables. Look at whether the comparable cars actually have the same packages. A comparable missing your Level 2 group, or with a smaller engine, isn’t comparable.
- Send it in writing. Send the adjuster the sticker and a short list of what’s missing, and ask for the valuation to be corrected. Oregon’s regulator puts it plainly: “If you believe your vehicle is worth more, you must prove a higher value.”
- If you still can’t agree. Your policy may have an appraisal provision, where each side picks an appraiser. In Oregon, insurers must reimburse reasonable appraisal costs when the final appraised value comes in higher than their last offer. Your state insurance department’s consumer line can also help.
Can I get the sticker for my car?
It depends on the brand and year, and the car is often gone by the time you need it. Our free check tells you from the VIN alone whether the original sticker is on file before you pay anything:
- Ford and Lincoln stickers come from Ford when Ford has released one.
- Most 2017-and-later Jeep, Ram, Dodge and Chrysler stickers come from Stellantis.
- Recent Subaru stickers come from Subaru.
- Other brands come through our licensed partner, when one is on file.
Our 84-VIN study shows which carmakers release stickers and how often.
If there’s no sticker on file, other proof still helps: the original purchase contract or buyer’s order, dealer invoices, photos of option badges and equipment, and on GM vehicles the option (RPO) codes, printed on the Service Parts Identification label in the glove box on older models (see GM build sheet).
This page is general information, not legal advice. Rules differ by state and by policy.
Last updated November 17, 2026.